NYC Employees PPO Plan

Screenshots
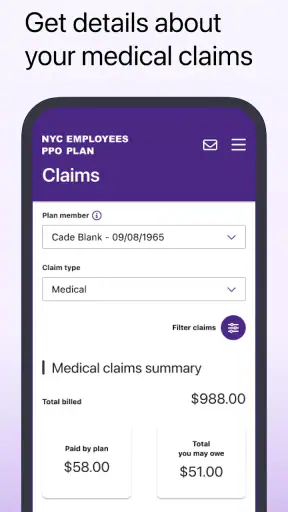
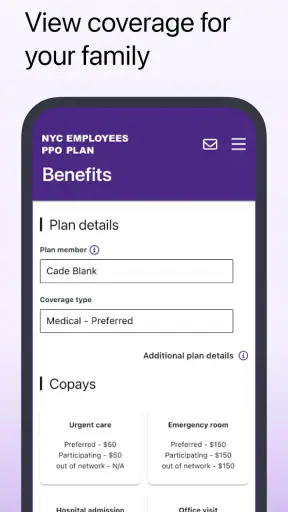
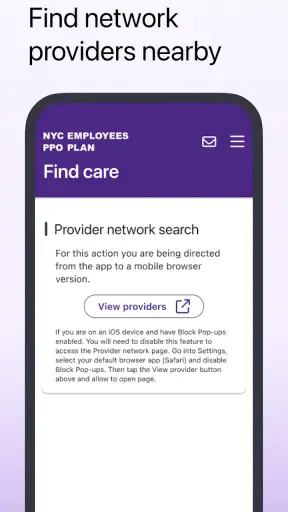
Details
- Rating
- 11.00 reviews
- Version
- 1.8.0
- Developer
- UNITED HEALTHCARE SERVICES, INC.
Analysis by Norviv
NYC Employees PPO Plan is a focused medical app rather than a general health companion. I see its main value in the moment when a member needs to move from having a health-plan card in a wallet to actually using that coverage with less friction. The app is intended for people enrolled in the NYC Employees PPO Plan, and access begins after receiving the member ID card. That detail matters: this is not an app I would install casually to browse before enrollment, but a practical digital doorway for an existing member.
My overall view is positive but deliberately narrow. The app can be useful when it puts plan-related access in one place, yet its usefulness depends heavily on whether you are the right member and what you need to do. It should not be mistaken for a replacement for a doctor, emergency services, a broad symptom checker, or a universal medical-record platform. For the intended audience, however, a dedicated plan app can be more convenient than repeatedly searching through paperwork or relying on a browser bookmark.
How the app fits into everyday plan management
The application comes from UNITED HEALTHCARE SERVICES, INC. and sits in the medical category. Its store summary points to a straightforward purpose: members use it after they receive their member ID card. I appreciate that this sets a practical boundary around the experience. The first question is not whether the app has an attractive collection of wellness tools; it is whether it helps a PPO member reach the information connected with their coverage when they need it.
That makes the app especially relevant during ordinary administrative moments. Imagine receiving your card, putting it somewhere safe, and then needing to confirm plan information before arranging care. A dedicated app gives you a second place to look, provided you have completed the required access steps. In my experience with plan-focused tools, that redundancy is valuable: the physical card remains useful at a clinic, while the phone becomes the easier option when you are away from home or organizing details for a family member.
The app is free, and its age classification is Everyone. Those points make it approachable for a broad group of members, including households where one person manages practical health-plan tasks for others. Still, “free” should be understood as the download cost, not as a promise that medical care itself has no cost. The app is a way to access plan-related services and information, not a benefit that changes the terms of the insurance plan.
The current version is 1.8.0, and the application requires an operating system version of 9 or later. That requirement is modest for many devices, but it is worth checking before handing an older phone to a parent or dependent and assuming installation will be possible. A plan app is only useful if the device can run it and the member can complete its access process comfortably.
The strongest reason to use a dedicated plan app
The clearest strength is focus. A general health app may be excellent for tracking habits, recording symptoms, or reading educational material, but it usually does not center the member’s relationship with a particular PPO plan. NYC Employees PPO Plan is built around that narrower relationship. For the right user, less scope can be an advantage because it keeps attention on coverage-related needs instead of mixing insurance tasks with unrelated wellness content.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
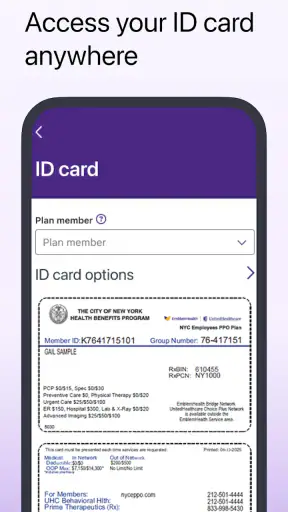
I also think the app makes sense as a companion to the physical member ID card rather than a replacement for it. My practical advice would be to keep the card available, install the app once access is ready, and treat the two as complementary. If a provider asks for card details, the physical card may still be the fastest item to hand over. If you are preparing for an appointment, checking information at home, or helping someone who is not standing beside you, the phone may be easier.
Another useful insight is that timing matters. Installing before receiving the member ID card may not deliver much value, because the store summary specifically frames access around that card. I would wait until the card is available, then set up the app while the relevant information is close at hand. This avoids a common frustration with member portals: downloading first, reaching a sign-in barrier, and then having to put the task aside until the enrollment materials arrive.
There is also a household workflow worth considering. If you help a spouse, parent, or other family member with appointments, the app can serve as part of your preparation routine, but I would avoid treating your phone as the only record. Keep important plan details in the original member materials and use the app for convenient access. That approach reduces the risk of being caught without information if the phone is unavailable, uncharged, or replaced.
Where the experience may become frustrating
The same specialization that makes the app useful also limits its audience. Someone looking for medication reminders, fitness tracking, symptom guidance, telehealth discovery, or a broad personal health dashboard may find this app too narrow. I would skip it if your main goal is general health management rather than handling the practical side of the NYC Employees PPO Plan.
Access dependency is another meaningful point of friction. A person who has not received the member ID card may not be able to make meaningful use of the app yet. That is not necessarily a flaw in the design; it reflects the app’s role. Still, it means the download is not an instant solution for someone who has just heard about the plan and wants to explore everything immediately.
I would also keep expectations realistic about convenience. A mobile interface can reduce the need to carry papers, but it cannot remove every step involved in arranging care. You may still need to speak with a provider, confirm details directly, or use another channel for a task that falls outside the app’s intended role. The app should make plan access simpler, not create the impression that every insurance question can be settled from a phone.
Privacy and device habits deserve attention too, even without turning the review into a technical checklist. This is a medical application, so I would use it on a personal device, keep the operating system updated, and avoid leaving the phone unlocked when sharing it with others. If you manage information for a family member, take a moment to confirm whose details you are viewing before an appointment. That small habit is more important than any cosmetic convenience.
Practical ways I would use it
My first recommended workflow is simple: receive the member ID card, install the app, complete access while the card is available, and then open it once more before the first planned visit. That second check is useful because it catches avoidable problems while you are still at home rather than in a waiting room. I would also make sure I know where the physical card is stored, since the app and card serve different purposes.
A second workflow is appointment preparation. Before contacting a provider, I would use the app as one part of a short checklist: have the member ID card nearby, review the information available through the app, write down the question I need answered, and keep the provider’s contact details separate. This prevents the common mistake of opening a plan app without knowing what information you actually need.
A third use case is travel within the city or a busy workday. If the card is not in your bag, a phone-based plan tool can be more convenient than returning home for paperwork. I would still avoid assuming that a digital view will always be accepted in every situation. Carrying the physical card, or at least knowing where it is, remains sensible for visits where staff specifically request it.
For a family helper, I would create a routine rather than relying on memory. Check the app before an appointment, compare the visible member details with the correct card, and save questions for the appropriate plan or provider contact. The non-obvious benefit here is organizational: the app can become a prompt to prepare, not merely a place to look after something goes wrong.
How it compares with the usual alternatives
The most obvious alternative is the physical member ID card. The card wins for simplicity, immediate recognition at a clinic, and independence from battery life or an internet connection. The app wins when you need plan-related access while away from your documents or when you are organizing information before a visit. I would not choose one over the other; I would use the app to supplement the card.
A mobile browser or desktop portal may be preferable for people who dislike small screens, have difficulty navigating phone apps, or need to work through a longer administrative task. A larger display can make reading and comparing information easier. On the other hand, the dedicated app is naturally better suited to someone who wants a plan-specific entry point on a phone instead of searching for the correct website each time.
General medical apps are a different category altogether. They may help with wellness routines or personal records, but they are not automatically better for NYC Employees PPO Plan access. If your question is about managing this particular coverage relationship, a focused plan app is the more logical first place to look. If your question is about symptoms, treatment decisions, or ongoing health tracking, another kind of tool may be more appropriate, and a qualified clinician should remain the authority for medical advice.
The app’s reception suggests that it is landing well with at least part of its audience: it holds a 4.7 average from around 174 ratings, with over 10 thousand installs. I treat those figures as encouraging rather than conclusive. A plan app can receive strong feedback simply because it solves a specific administrative problem for enrolled members, while still being irrelevant to people outside that group. The rating supports confidence in its general usefulness, but it should not override the question of whether its purpose matches yours.
Who should install it, and who should pass
I would recommend NYC Employees PPO Plan to an NYC Employees PPO Plan member who has received the member ID card and wants a convenient mobile route to plan-related access. It is also a sensible choice for someone who frequently helps a family member prepare for care and prefers having a dedicated app rather than depending entirely on paper documents.
I would be more cautious for a person who has not yet received the card, is using an older device that may not meet the operating-system requirement, or expects a complete personal-health suite. In those situations, the app may not solve the immediate problem. The physical card, a larger-screen portal, or direct contact with the relevant plan or provider may be a better first step.
People who need urgent medical attention should not delay care while trying to navigate an app. Likewise, someone seeking a diagnosis, emergency guidance, or individualized treatment should use the appropriate medical service. This application belongs in the administrative and coverage-access part of a healthcare routine, not at the center of a clinical decision.
My final assessment
After looking at the app through the needs of its intended members, I see NYC Employees PPO Plan as a practical specialist rather than an all-purpose health application. Its strongest quality is the same thing that limits it: it concentrates on access for people connected to this specific NYC employees PPO coverage. For those members, that focus can be genuinely helpful, especially when preparing for care, managing information away from home, or reducing dependence on scattered paperwork.
The trade-off is clear. You need the member ID card to begin using it meaningfully, and the app should not be expected to replace the card, a provider, emergency services, or every other plan-support channel. I would install it after receiving the card, test access before an appointment, keep the physical card available, and use a browser or direct assistance when a larger or more personal interaction is needed.
With a 4.7 average and a free download, it is an easy recommendation for the right audience, but not a universal one. The best reason to choose this app is not the promise of extra health features; it is the convenience of having your NYC Employees PPO Plan access ready when an ordinary healthcare task suddenly becomes time-sensitive.
Frequently Asked Questions
01What is the NYC Employees PPO Plan app used for?
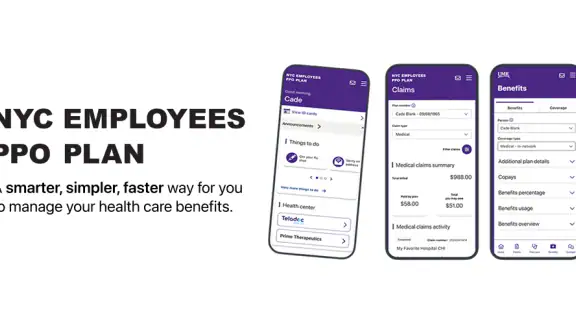
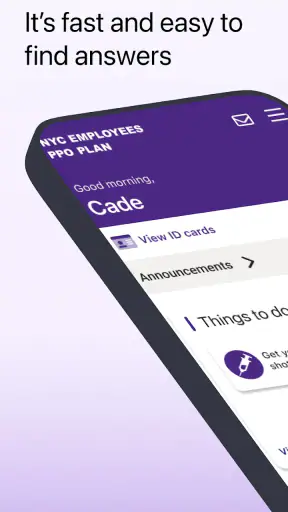
The NYC Employees PPO Plan app is designed to help eligible New York City employees and covered dependents manage health-plan information in one place. Depending on the available features, members may be able to review benefits, locate participating providers, access identification details, check claims or coverage information, and find customer-service contacts. It is primarily a convenience tool and does not replace the official plan documents or personalized assistance from the insurer.
02Who can use the NYC Employees PPO Plan app?
Access is generally intended for members enrolled in the NYC Employees PPO Plan, including eligible city employees, retirees where applicable, and covered dependents. Registration may require information from your health-plan identification card, such as a member ID or group number. Eligibility and available features can vary according to employment status, plan enrollment, and the organization administering the benefits, so users should confirm their coverage before relying on the app.
03Can I use the app to find doctors and hospitals in network?
The app may provide tools for searching doctors, specialists, hospitals, laboratories, and other healthcare facilities that participate in the PPO network. Before scheduling care, review the provider’s current network status and confirm that the specific location and service are covered, since participation can change. It is also wise to contact the plan directly when treatment is expensive, specialized, or subject to referrals, authorization, or other limits.
04Can members view claims, benefits, and coverage details through the app?
Many health-plan apps allow members to review benefit summaries, claims activity, deductibles, out-of-pocket amounts, and explanations of benefits, although the exact functions may differ by version and plan administrator. Information can take time to appear after a provider submits a claim. For a final coverage decision, always consult the official plan documents or contact member services, particularly for exclusions, prior authorization, and emergency-care questions.
05Is the NYC Employees PPO Plan app free and safe to download?
The official app is typically available at no additional charge to eligible plan members, although normal mobile-data charges may apply. Download it only from a verified Apple App Store or Google Play listing and check the publisher name before installing. The app may request personal and health-related information, so use a strong password, enable device security, avoid sharing login details, and review its privacy policy and permissions.


